
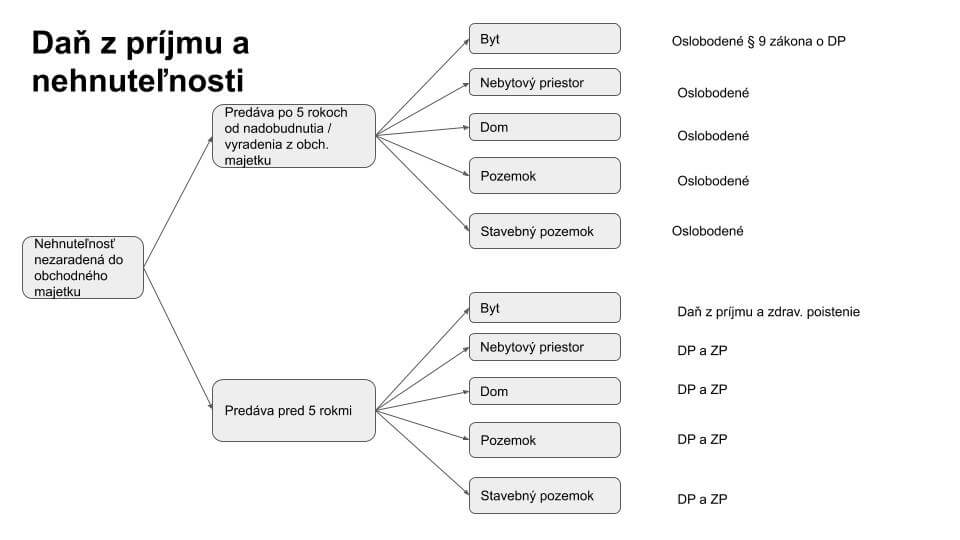
Income tax exemption on the sale of property
The sale of a property or flat is exempt from income tax if it takes place more than 5 years after the property was acquired. The date of acquisition is primarily taken to be the date of entry in the Land Register, but you should always also check whether the contract contains any conditions precedent relating to payment of the purchase price, or other circumstances that would defer the acquisition to a later date.
The five-year period starts from the latest possible point – entry in the Land Register, payment of all or part of the purchase price, signature of an addendum to the contract and so on – and ends at the earliest possible point, whether that is signature of a reservation agreement, payment of a deposit, signature of the contract, payment of the purchase price or entry in the Land Register. In other words, the start and end of the period are taken as the two points least favourable to the taxpayer: the period required for the exemption starts as late as possible and ends as early as possible.
If you wish to save time and money when preparing property transfer contracts or dealing with tax questions related to property sales, it is best to contact lawyers or property specialists, such as the law firm www.navratlaw.com and the estate agency www.realtuls.sk
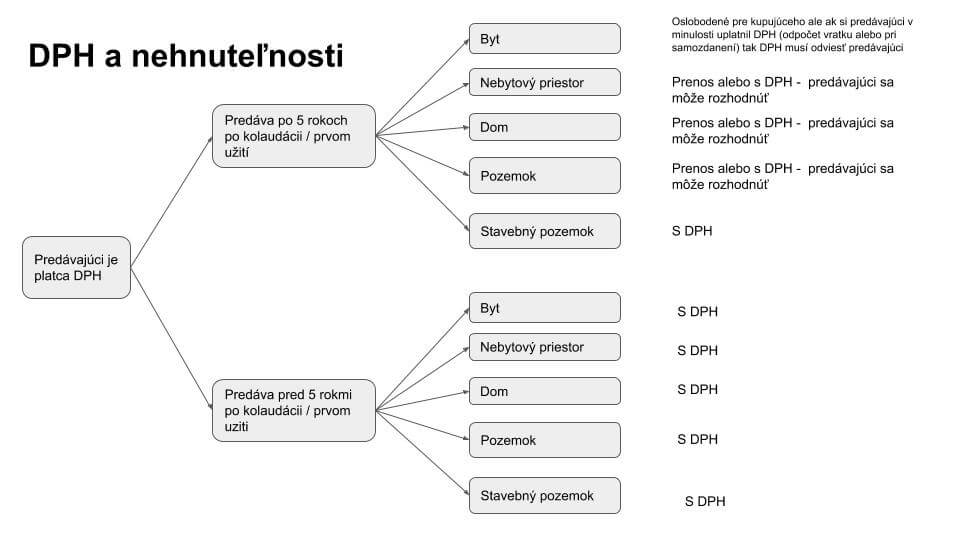
VAT exemption on the sale of property
Where a property is sold by a person not registered for VAT, VAT does not come into play. Where the seller is VAT-registered, several scenarios are possible: the sale may be exempt from VAT, the price may be invoiced with VAT, or the price may be invoiced without VAT with the obligation to account for VAT passing to the buyer (reverse charge). The VAT treatment also varies according to the type of property – a different regime applies to the sale of a flat, a house, land and building land.
Daň, DPH a odvody pri kúpe a predaji nehnuteľnosti
| Kúpna cena | DPH | Cena+DPH | Zhodnotenie | Predajná cena | DPH | Cena+DPH | rozdiel DPH | Základ dane z príjmu | Sadzba dane | Daň z prijmu | Prijem po zdanení | Sadzba zdravotného poistenia | Zdravotné poistenie | Príjem po odvodoch a dani | Sadzba dane z dividend | Daň z dividend | Prijem po dani z dividend |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Platca DPH | |||||||||||||||||
| 100 000 € | 20 000 € | 120 000 € | 0,50 | 150 000 € | 30 000 € | 180 000 € | -10 000 € | 50 000 € | 0,21 | 10 500 € | 39 500 € | 0,07 | 2 765 € | 36 735 € | |||
| Neplatca DPH | |||||||||||||||||
| 120 000 € | 0,50 | 180 000 € | 0 € | 60 000 € | 0,21 | 12 600 € | 47 400 € | 0,07 | 3 318 € | 44 082 € | |||||||
| Fyzická osoba | |||||||||||||||||
| 120 000 € | 0,50 | 180 000 € | 0 € | 60 000 € | 0,19 | 6 650 € | 47 100 € | 0,14 | 8 400 € | 38 700 € | |||||||
| 0,25 | 6 250 € | vrátenie dane po úhrade odvodov | 2 100 € | 40 800 € | |||||||||||||
| Platca DPH oslobodenie po 5 rokoch od vyradenia z majetku | |||||||||||||||||
| 100 000 € | 20 000 € | 120 000 € | 0,50 | 150 000 € | 30 000 € | 180 000 € | -10 000 € | 50 000 € | 0,00 | 0 € | 50 000 € | 0,07 | 3 500 € | 46 500 € | |||
| Neplatca DPH oslobodenie po 5 rokoch od vyradenia z majetku | |||||||||||||||||
| 120 000 € | 0,50 | 180 000 € | 0 € | 60 000 € | 0,00 | 0 € | 60 000 € | 0,07 | 4 200 € | 55 800 € | |||||||
| Fyzická osoba oslobodenie po 5 rokoch | |||||||||||||||||
| 120 000 € | 0,50 | 180 000 € | 0 € | 60 000 € | 0,00 | 0 € | 60 000 € | 0,00 | 0 € | 60 000 € | 0,00 | 0 € | 0 € | ||||
| 0,00 | 0 € | ||||||||||||||||
| Kúpna cena | DPH | Cena+DPH | Zhodnotenie | Predajná cena | DPH | Cena+DPH | rozdiel DPH | Základ dane z príjmu | Sadzba dane | Daň z prijmu | Prijem po zdanení | Sadzba zdravotného poistenia | Zdravotné poistenie | Príjem po odvodoch a dani | Sadzba dane z dividend | Daň z dividend | Prijem po dani z dividend |
| Platca DPH | |||||||||||||||||
| 200 000 € | 40 000 € | 240 000 € | 0,50 | 300 000 € | 60 000 € | 360 000 € | -20 000 € | 100 000 € | 0,21 | 21 000 € | 79 000 € | 0,07 | 5 530 € | 73 470 € | |||
| Neplatca DPH | |||||||||||||||||
| 240 000 € | 0,50 | 360 000 € | 0 € | 120 000 € | 0,21 | 25 200 € | 94 800 € | 0,07 | 6 636 € | 88 164 € | |||||||
| Fyzická osoba | |||||||||||||||||
| 240 000 € | 0,50 | 360 000 € | 0 € | 120 000 € | 0,19 | 6 650 € | 92 100 € | 0,14 | 16 800 € | 75 300 € | |||||||
| 0,25 | 21 250 € | vrátenie dane po úhrade odvodov | 4 200 € | 79 500 € | |||||||||||||
| Platca DPH oslobodenie po 5 rokoch od vyradenia z majetku | |||||||||||||||||
| 200 000 € | 40 000 € | 240 000 € | 0,50 | 300 000 € | 60 000 € | 360 000 € | -20 000 € | 100 000 € | 0,00 | 0 € | 100 000 € | 0,07 | 7 000 € | 93 000 € | |||
| Neplatca DPH oslobodenie po 5 rokoch od vyradenia z majetku | |||||||||||||||||
| 240 000 € | 0,50 | 360 000 € | 0 € | 120 000 € | 0,00 | 0 € | 120 000 € | 0,07 | 8 400 € | 111 600 € | |||||||
| Fyzická osoba oslobodenie po 5 rokoch | |||||||||||||||||
| 240 000 € | 0,50 | 360 000 € | 0 € | 120 000 € | 0,00 | 0 € | 120 000 € | 0,00 | 0 € | 120 000 € | 0,00 | 0 € | 0 € | ||||
| 0,00 | 0 € |
DPH - ak bola DPH uplatnená pri kúpe (odpočet albo samozdanenie), tak na predaj sa môže vzťahovať DPH aj po piatich rokoch pri prenose DPH alebo oslobodení DPH
DPH - vyradenie z majetku môže mať dopady na DPH (oslobodenie, prenos, odpočet)
Read more about property on our blog
Agreement on Transfer of Flat Ownership
Preparing to sell or buy a flat involves a series [...]

Brokerage Agreement for Estate Agencies
Brokerage agreement It is fair to say that this is [...]
Essential Terms When Concluding a Purchase Agreement
This Act was passed by the National Council of the [...]
Brokerage Agreement
This agreement is concluded between you and an estate agency [...]
Flat Purchase Agreement and Price as an Essential Term
The essential elements that every purchase agreement must contain are [...]